Helping Small Businesses Grow Since 1981
Somewhere in Nevada this morning, a business owner signed a rent check and thought the same thing thousands of owners have thought before them.
I would rather be paying this to myself.
That thought is where our story starts. Forty-five years ago, it is where ours started too.
It Started With a Belief
In 1981, a group of Nevadans started a nonprofit around a simple one: that a good idea deserves a real chance to grow.
Not a guaranteed chance. Not an easy one. A real one, of the kind that turns a leased storefront into a deed with your name on it.
Forty-five years later, that belief has helped fund thousands of small businesses, put down roots in communities across the state, and given Nevada entrepreneurs the chance to go from renting their space to owning it.
This year we are celebrating that milestone. Not because of what NSDC has become, but because of what Nevada’s small business owners have built with a little support and a lot of determination.
How the Dream Gets Built
Every small business eventually reaches a point where growing means putting down permanent roots. A bigger shop. A second location. A building that finally fits.
That is the point where most owners run into the SBA.
Let’s strip away the jargon. The SBA 504 program is long-term, fixed-rate financing that lets a small business owner purchase, build, renovate, or expand the commercial property and major equipment they operate from. In plain terms: it helps Nevada’s entrepreneurs stop paying someone else’s mortgage and start building their own.
Here’s the short version of how it is structured. A bank or credit union covers about 50% of the project. NSDC covers about 40% through an SBA-backed debenture, at a rate that is fixed at closing. You bring about 10% as a down payment. Startups and special-purpose buildings typically need a little more, usually 15%.
That 10% is the number most owners get wrong. They assume commercial property works like a house and demands 20% or 30% down, so they never make the call.
You cannot get an SBA 504 loan without a Certified Development Company, and that is exactly what NSDC is. We handle the SBA side of the deal so you can keep running your business while it moves.
We will also tell you plainly what 504 is not for. It is not financing for pure investment property. You have to occupy the majority of the building yourself. If your plan does not fit the program, you will hear that from us early, not after months of paperwork.
What Forty-Five Years Actually Looks Like
It looks like a building.
It looks like a payroll somebody signs on the 15th and the 30th. A parking lot that fills up. A sign that stays put long enough that people give directions by it.
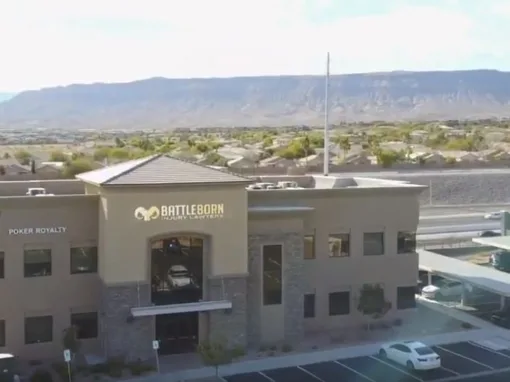
A few of the Nevada businesses that went from renting to owning.
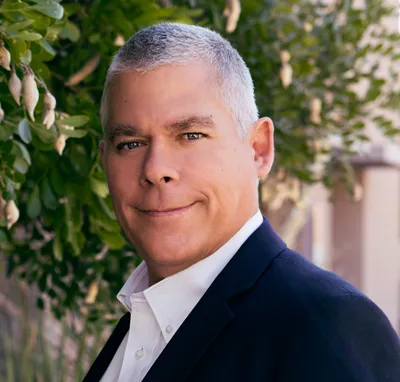
“When we started in 1981, we were making a bet on Nevada’s small business owners, and they have proven us right thousands of times over.
Forty-five years later, what motivates us has not changed. Someone walks in with an idea and a lot of grit, and we get to help turn that into a building they own, a payroll they sign, and a place their community counts on. That never gets old.”
— Evan Dickson, President, NSDC
What Has Not Changed
The program has been revised over the decades. Rates move every month. The buildings have gotten bigger and the paperwork has moved online.
The part that has not changed is who answers the phone.
When you finance a building through NSDC, we stay on as your servicer for the life of the loan. Questions in year nine go to the same organization that walked you through year one. You are not calling a stranger. You are calling the people who helped you buy the place.
That was the point in 1981, and it is still the point now.
Still Renting?
If you have ever wondered what owning your space would actually take, that is a short conversation, and it costs nothing. Most of them start with one question about your current lease.
Or call Las Vegas (702) 877-9111 · Reno (775) 770-1240
This article is for general informational purposes only and does not constitute legal, tax, or financial advice. Loan terms, eligibility, and down payment requirements are subject to SBA guidelines and lender approval.